Offer Finance on Conservatories & Conservatory Installations
End-to-end compliance support for conservatory retailers and installers offering customer finance.
Understanding customer finance for conservatories
Customer finance is a way for homeowners to spread the cost of a conservatory project through repayments rather than paying the full price upfront. The project may include surveying, supply, installation and internal finishing.
Extras that may be eligible for finance include replacement roofs, premium glazing, bi-fold doors, flooring or underfloor heating. Finance may cover a combined project rather than one individual product, subject to the lender and agreement. The retailer’s role in presenting or arranging finance will affect its regulatory obligations.
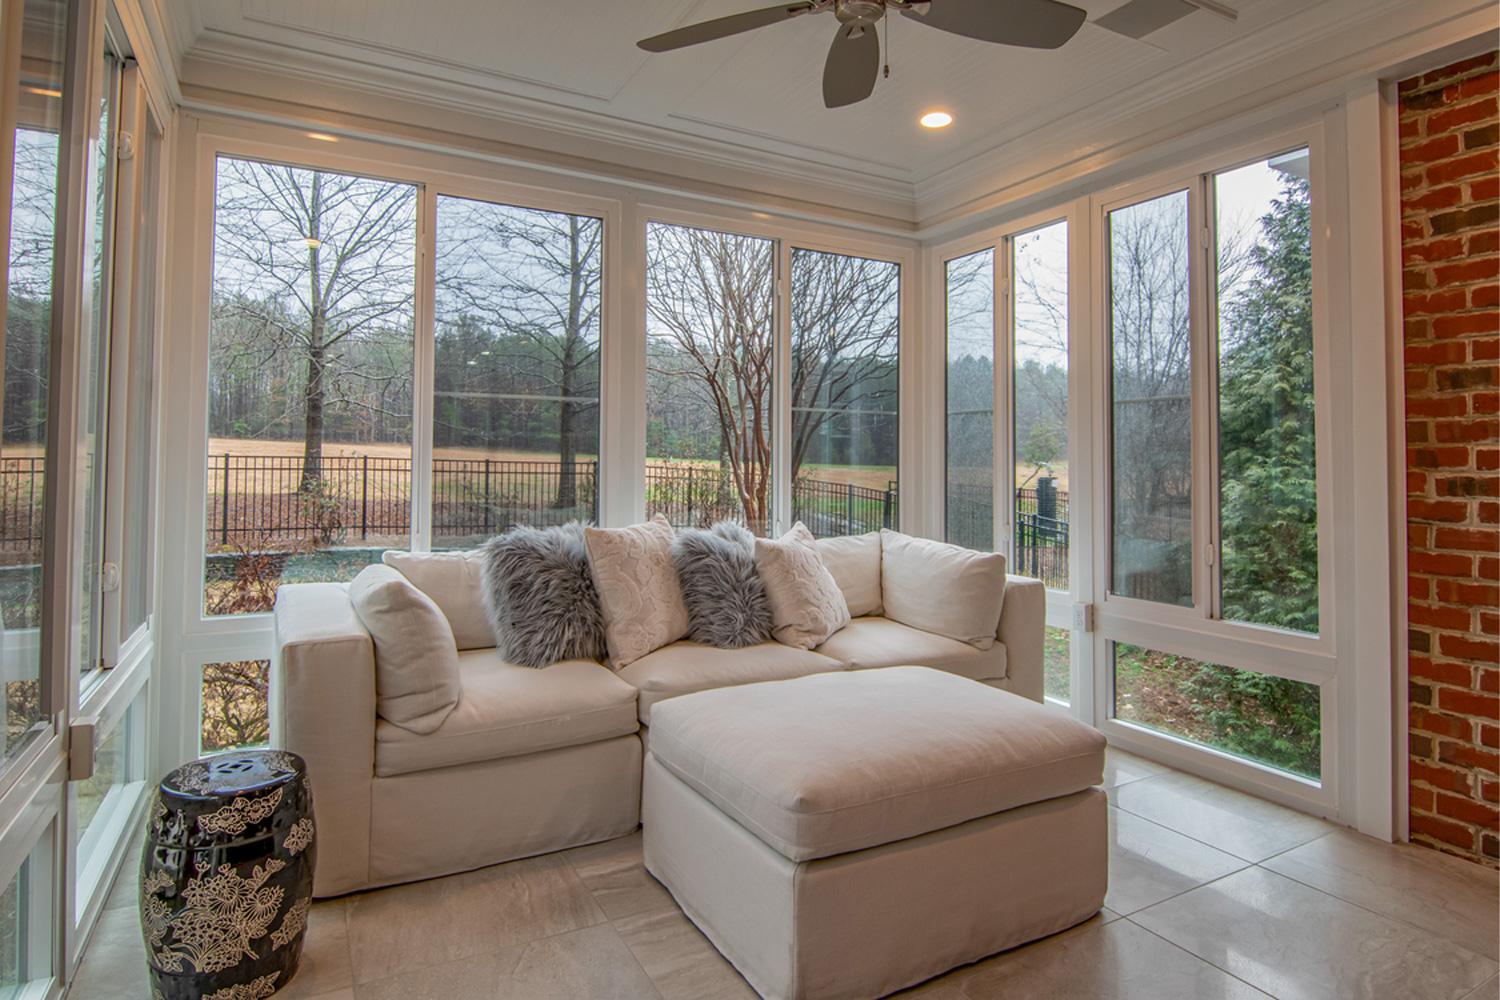
Why offer finance for conservatories?
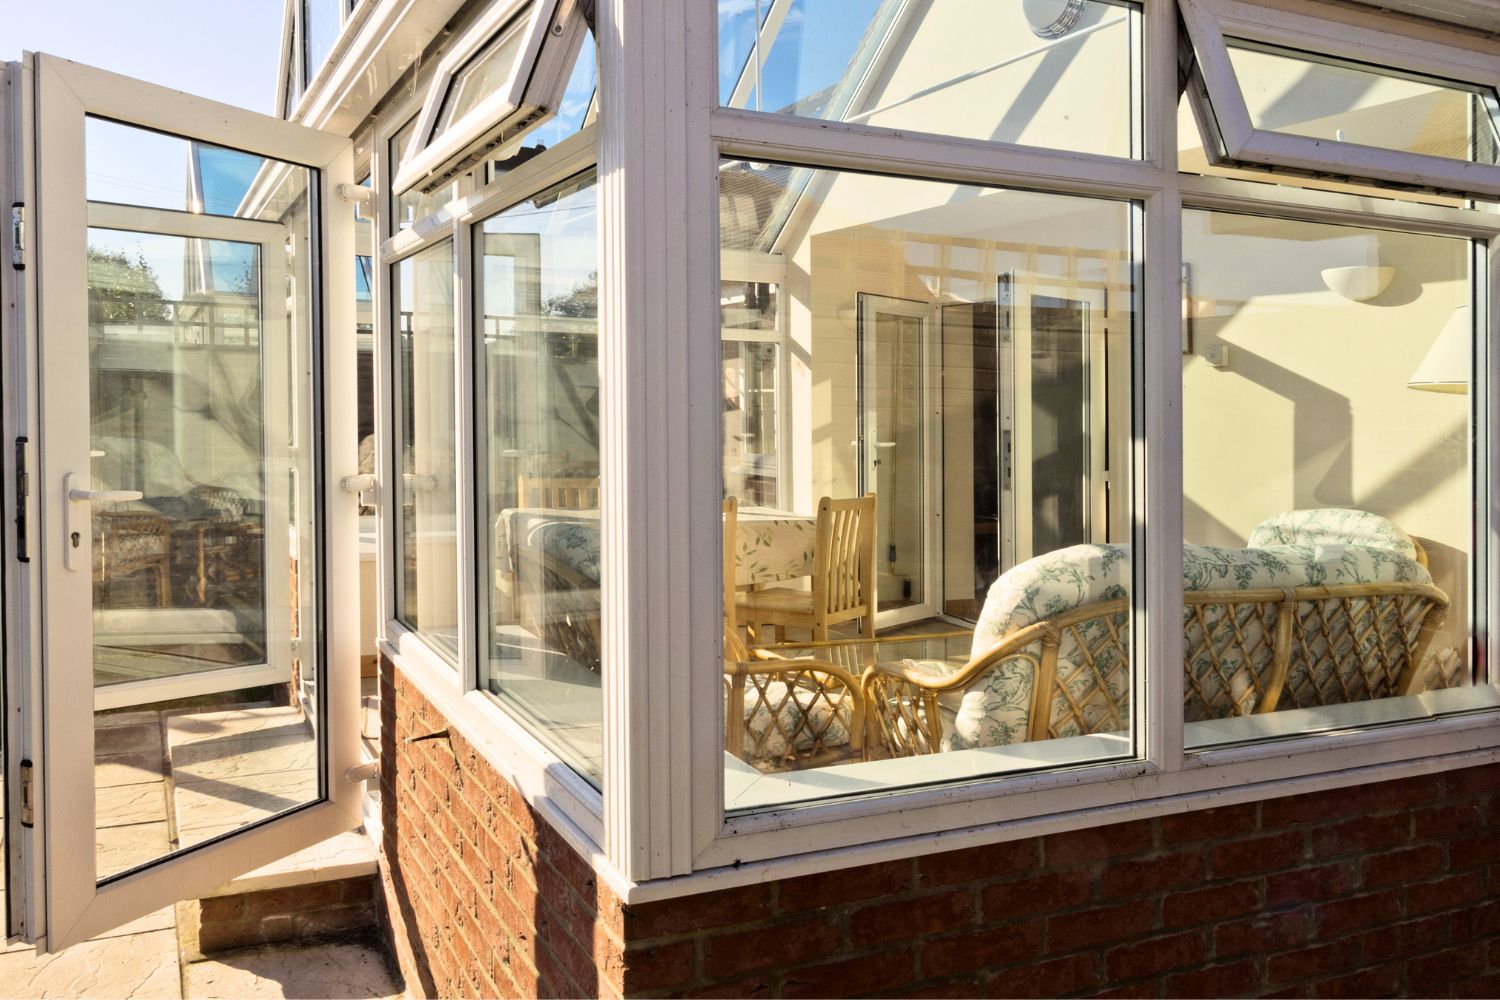
The total price of a conservatory project rises when customers choose upgraded glazing, doors, heating or finishing work. Finance gives customers another way to consider the cost, potentially allowing them to avoid postponing the project while they save for the full amount.
This may help convert enquiries and sell upgrades. Finance can be introduced at the quotation stage, during a home survey in the showroom, as well as online.
What conservatory finance options can you offer customers?
Conservatory finance can be structured in different ways depending on the lender and the value of the project.
0% Finance
Interest-free credit allows eligible customers to spread the cost without paying interest, while fixed-rate finance involves interest charged at an agreed rate.
Interest-bearing agreements
Deposits, repayment periods, eligibility criteria and the total amount payable vary by provider, so retailers should confirm the available terms before presenting finance to customers.
Longer-term consumer credit agreements
Longer-term finance may help spread the cost of larger projects, including installation and upgrades.
Buy now, pay later (BNPL)
Buy now, pay later allows customers to defer payment, although they need to understand when repayments begin and whether interest or charges apply.
Deferred payment plans
Interest-free deferred payment arrangements give customers an initial period without interest or payments, followed by repayments under the agreement. Fixed-term instalment plans provide repayments over a set period.
How can The Compliance Guys help?
The Compliance Guys can assess whether your conservatory business needs FCA authorisation and identify the appropriate permissions or alternative arrangements.
Support includes applications, business plans, financial forecasts, compliance policies and FCA correspondence. We also offer guidance on finance promotions, customer journeys, broker relationships and continuing compliance after authorisation.
Get your FCA application right first time!
Contact The Compliance Guys today on 01792 926 040 or email sales@thecomplianceguys.co.uk for more information about our bathroom finance and FCA authoristion support!
The compliance considerations
Introducing or arranging consumer finance may be a regulated activity, and the requirements will depend on the business’s actual role, from advertising finance to introducing customers or arranging credit. Unsuitable arrangements carry risks or misleading promotions, including complaints, reputational harm and potential regulatory action.
FCA Authorisation
A business may need authorisation if its activities constitute regulated credit broking, even if it does not lend the money itself.
Limited Permission, Full Permission, an appointed representative arrangement or an applicable introducer route may be relevant, depending on the business model.
Disclosure
Before committing, customers should understand applicable APR, interest, deposits, monthly repayments, agreement length and total amount payable.
Finance terms should match the project quotation, including any upgrades or optional work, and clearly state relevant conditions and charges.
Marketing
Finance promotions must be clear, fair and not misleading across websites, quotations, brochures, social media and showroom materials. Promotions must not hide conditions or imply guaranteed acceptance.
Customer Protection
Treat customers fairly, explain repayments clearly and avoid pressure during home surveys or sales appointments. There should be appropriate support for customers who need it, effective complaints handling and compliance with Consumer Duty obligations where applicable.
Using 3rd party credit brokers
There is a difference between conservatory businesses supplying and installing the project and a separate lender providing the credit. Customers receive a quotation, apply through the provider and enter an agreement if approved.
Following approval, surveys, manufacture and installation scheduling need to align with the agreed project and payment arrangements. Using an authorised broker does not automatically remove the retailer’s own regulatory responsibilities.
Why choose The Compliance Guys?
Authorisation made simple
The Compliance Guys help conservatory businesses to establish whether authorisation is required and then identify a suitable regulatory route.
Experts across sectors and application types
We support home improvement firms, retailers, installers and secondary credit brokers with Full Permission, Limited Permission, Variations of Permission, Change in Control applications and New Firm Registrations.
End-to-end support, every step of the way
We cover application preparation, document organisation, FCA correspondence and responses to further information requests, plus ongoing compliance support.
Personalised, professional guidance
Our advice is tailored to the company’s operations, with support on business plans, financial forecasts, regulatory documents and customer finance journeys.
Frequently Asked Questions
What is a credit broker?
A credit broker is an intermediary between customers and lenders. A conservatory retailer may be involved if it introduces customers to a finance provider.
What is a lending licence?
‘Lending licence’ is informal terminology; the required FCA permissions depend on the activities undertaken.
How do I register with the FCA?
Businesses must identify their regulated activities and required permissions. We can help prepare applications, supporting documents and responses to FCA queries.
Does FCA authorisation expire?
Authorisation does not generally expire after a fixed period, but firms must continue meeting their obligations and review permissions when activities change.
What parts of a conservatory project can customers finance?
Customers can finance supply and installation, replacement roofs, upgraded glazing, doors and eligible finishing work if permitted by the lender and the finance agreement determine it appropriate.
Can customers finance both the conservatory and installation?
A finance agreement may cover a combined supply-and-install package, depending on the provider and the way the project is contracted and priced.
What finance options do conservatory customers expect?
Customers may expect a range of options including interest-free credit, fixed-rate repayments and deferred-payment options. The terms, deposits requirements and eligibility criteria are likely to vary by provider.
Can customers finance a replacement conservatory roof?
Replacement roofs and associated work may qualify where supported by the finance product.
Can customers finance conservatory upgrades and extras?
Extras such as premium glazing, bi-fold doors, heating, flooring and blinds may be covered by finance, but the quotation and agreement must reflect the items that are actually included.
Does offering finance increase conservatory sales?
Finance may make a project more accessible and encourage some customers to consider upgrades, but results are not guaranteed.
Is “0% conservatory finance” the same as buy now, pay later?
0% credit involves no interest under the agreed terms, whereas BNPL generally defers payment or uses a different repayment structure. However, terms and conditions can differ.
Do conservatory retailers need FCA authorisation to offer finance?
This depends on the business’s activities, its role in introducing or arranging finance and whether an applicable exemption or authorised arrangement applies. It is important to establish the position before promoting or arranging finance.
Get in touch...
Call us for a chat on 01792 926 040, or fill out the form and we will get back to you as soon as possible.
Alternatively, you can also connect with us on LinkedIn.